by Justin J. Long CFP® on Oct 2, 2026, 7:20:39 AM
Where We Were
2025 was another great year for equities, as well as fixed income – despite a cloud of despair present in so many minds around the country. President Trump rode a strong wave of economic hope and goodwill early in the year, mostly focused on dismantling selective government overreach and lowering taxes. That goodwill was quickly dashed against the rocks of see-saw tariff and trade policy changes, retaliation by quite important (and powerful) trade partners, as well as an unwise attack on the Federal Reserve and the members of the FOMC. As a result, confidence as well as economic and earnings growth projections tapered off between the end of Q1 and into Q2. That both coincided with, and likely caused, an overdue equity market correction between March and April.
Market conditions and confidence rose again after Q2 earnings results started to come in, as they did not reflect the doom-and-gloom forecasts of many an economist and talking head. Corporate earnings rode a tailwind of stronger-than-expected incomes, spending and net worth, as well as expanding margins and cash flow led by growth companies. Strong earnings results and forecasts continued throughout the rest of the year. Equity returns were strong across the board and led by foreign emerging markets (+34%), foreign developed markets (+31%), and US large cap growth (again, +22%). The S&P 500 rose +18%. Fixed income returns were extremely even across the board and generally well above their long-term averages, buoyed by tapering inflation and overall US economic growth projections (after inflation) of a bit less than 2%. The Aggregate Bond index rose 7%, while 7-10 year Treasurys, investment-grade corporates, mortgage-backed, and high yield bonds all returned 8+% on the year, proving once again that the Chicken Littles (“60/40 is dead”) should remain unheeded.
Where We Are
Source: Factset
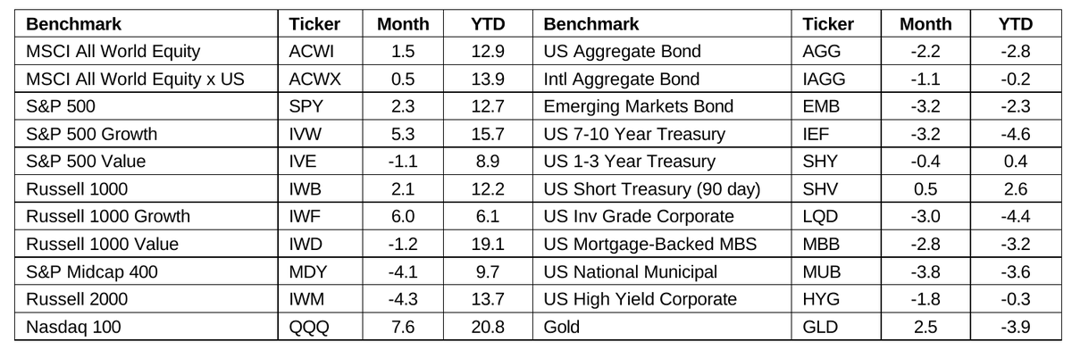
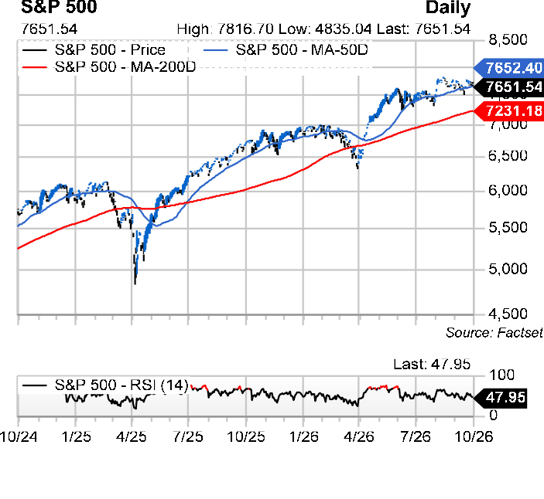
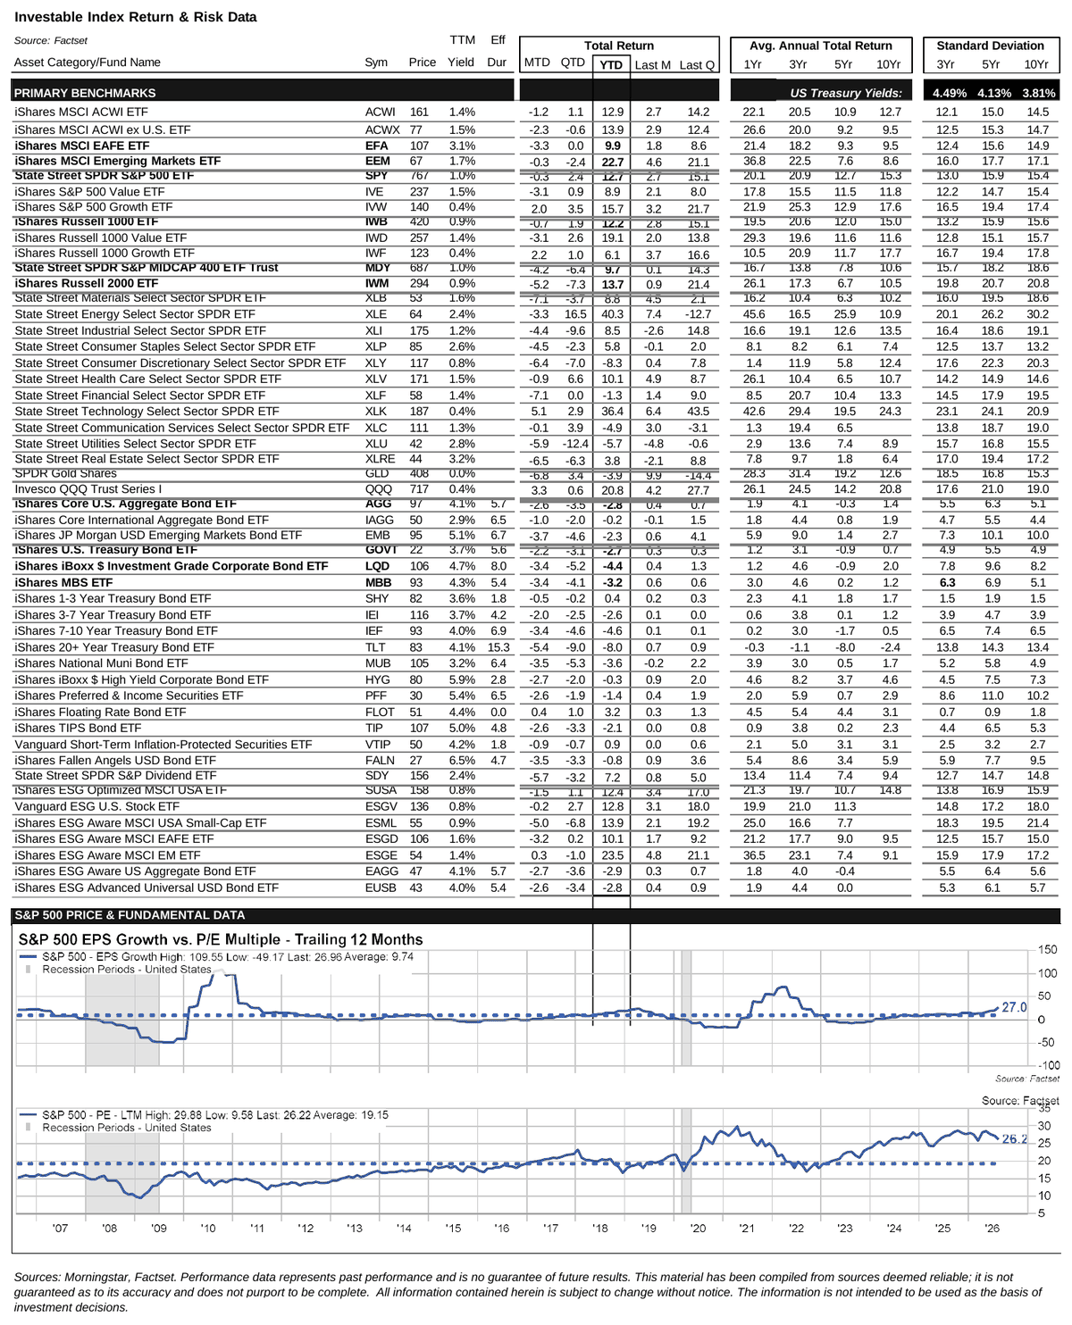
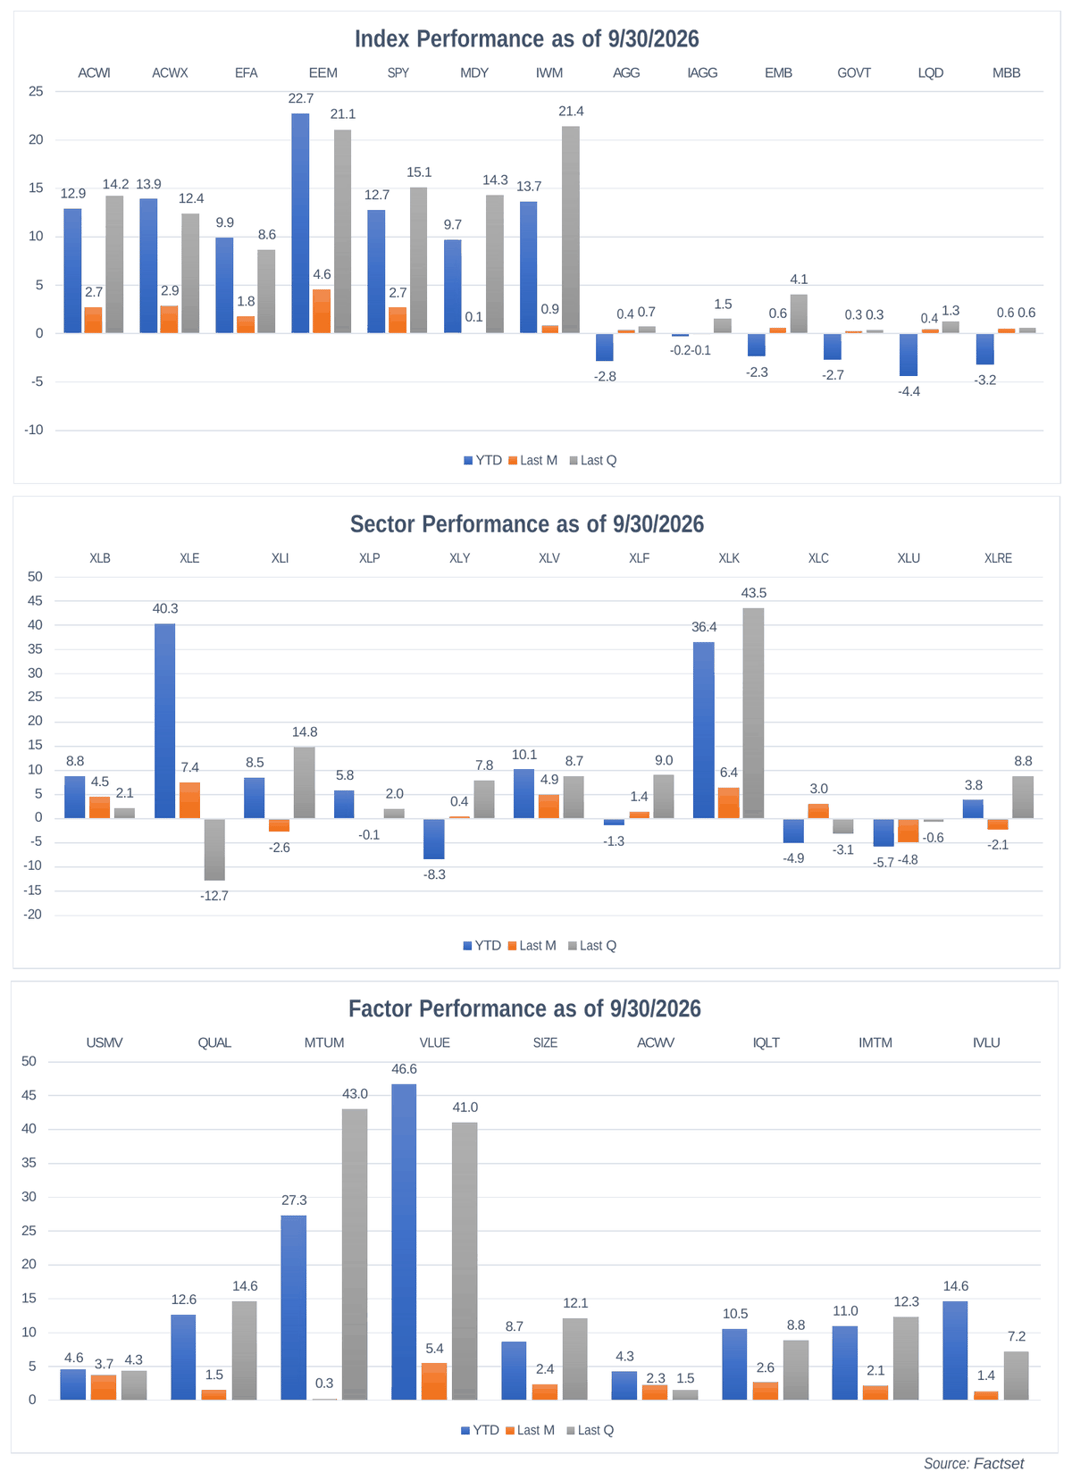
The S&P 500 rose in September, yet remains 2% off its high. The S&P 500 index gained 2.3% last month, enjoying earnings tailwinds. Global stock indexes lagged US Large Cap, now only about 1% higher YTD. Mid and Small Cap were both off for the month. Within the S&P 500, Growth was up 5% for the month, while Value was off -1%.
The US Aggregate Bond index is off -2.8% YTD, reflecting (mostly) energy-related inflation pressures. The 10-year T-Note yield is at 5.25%.
Q2 Results. With 100% of S&P 500 constituents reporting, 77% beat revenue estimates, with the average upside surprise being 3%. 87% beat EPS estimates, with the average beat coming in at 26%. Actual Q2 EPS growth was 52% vs. the 19% expected at the beginning of Q2.
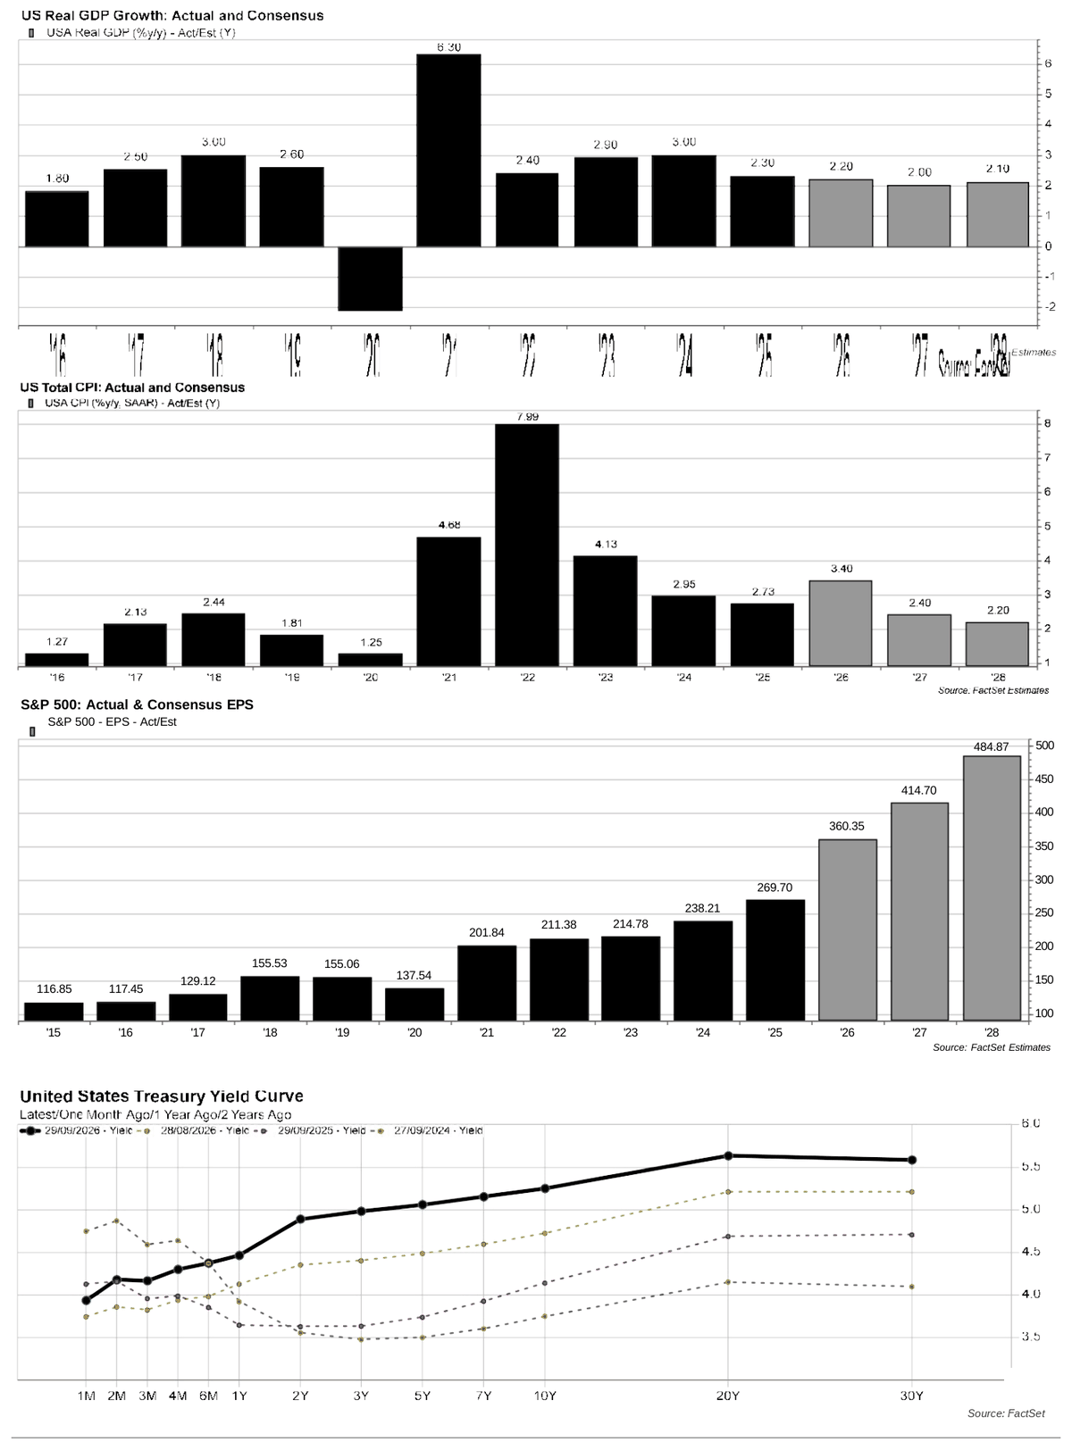
S&P 500 earnings expectations. For 2025, final EPS was $270/share, up 13% vs. 2024. The 2026 estimate is $360 (+33%), 2027 is $415 (+15%), and 2028 is $485 (+17%). P/E ratios for ’26-28 are 21x, 19x and 16x. The P/E-to-Growth (PEG) ratios are 0.6, 1.3 and 0.9. The average EPS growth rate over the past 20 years is 7.5%; the average trailing and forward P/E ratios are 20x and 17x, while the 20-year average trailing PEG ratio is 2.6x. The consensus median price target for the SPX is 9302 vs 9230 a month ago and 9095 sixty days ago, for an implied price return of +22%. If achieved this calendar year, the implied total return for the S&P 500 in 2026 would be 35%.
Where We’re Headed
Corporate earnings continue to rise, but energy sector dynamics are killing the vibe. We’ve been highlighting the exceptional growth in earnings and margins this year, so that is no surprise. But another positive development is that sector growth participation has widened, extending above-average growth expectations to beyond the realm of Info Tech.
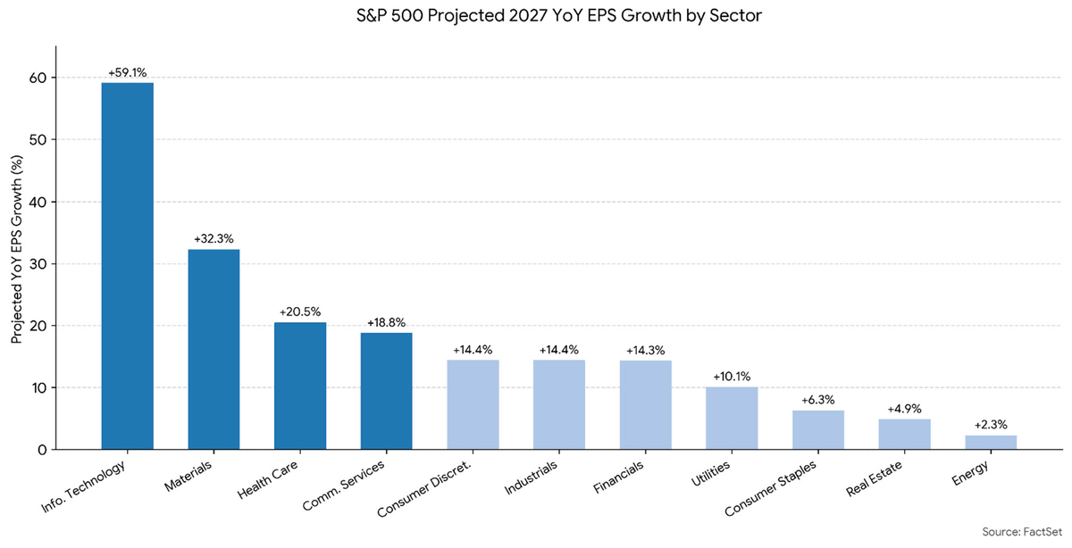
As much as this is good news (that EPS changes are one of the most important, if not the most important, drivers of equity prices), inflation relative to energy has risen again. Higher gas and diesel prices put upward pressure on production and transportation prices for raw materials, finished goods and food (as well as other items).
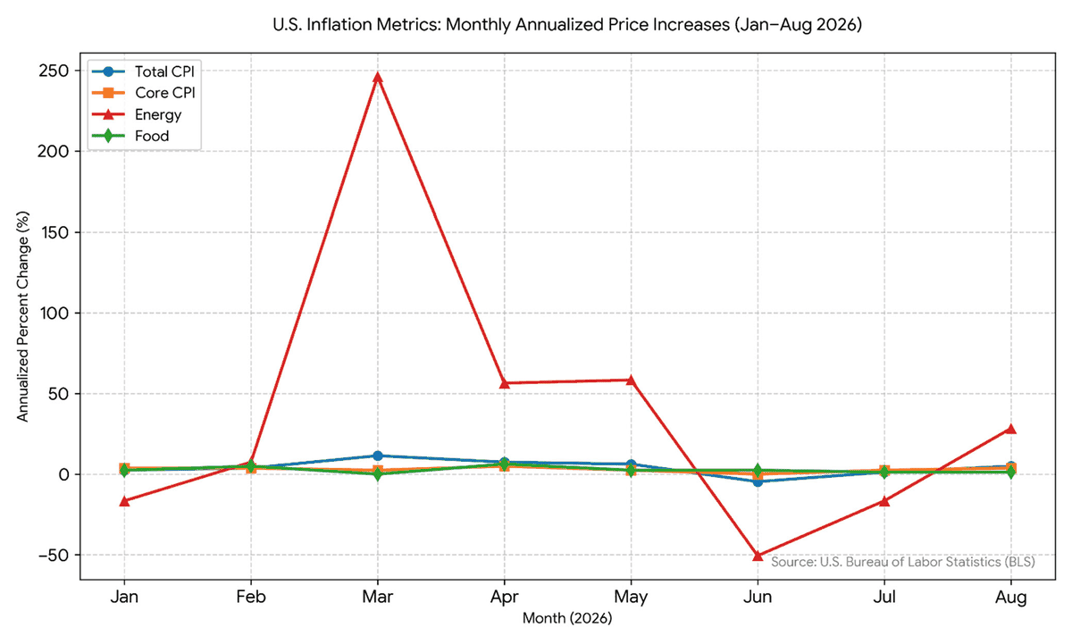
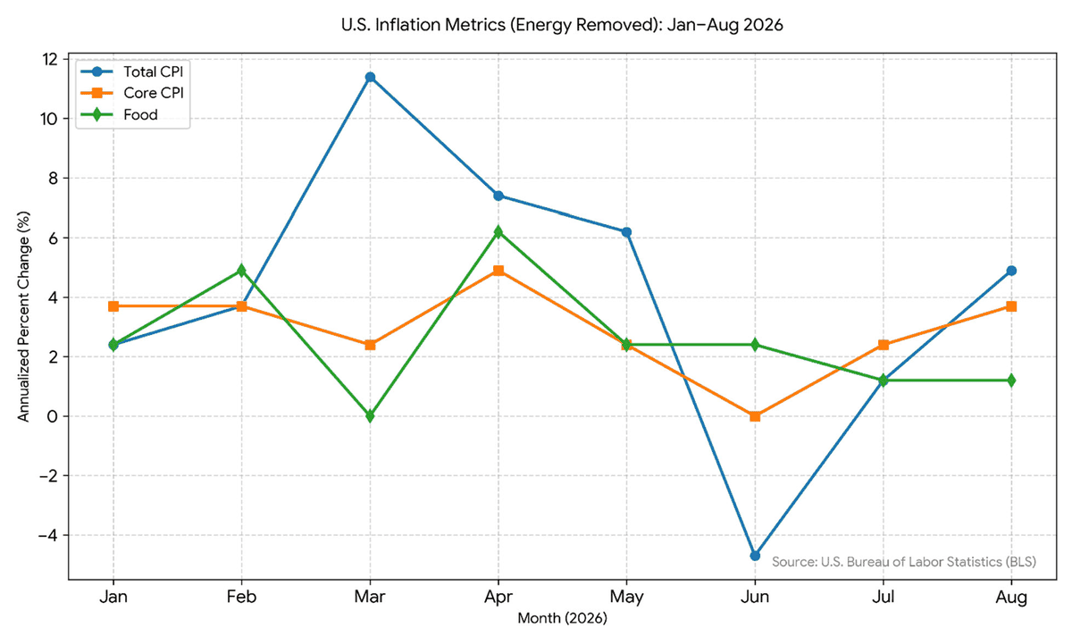
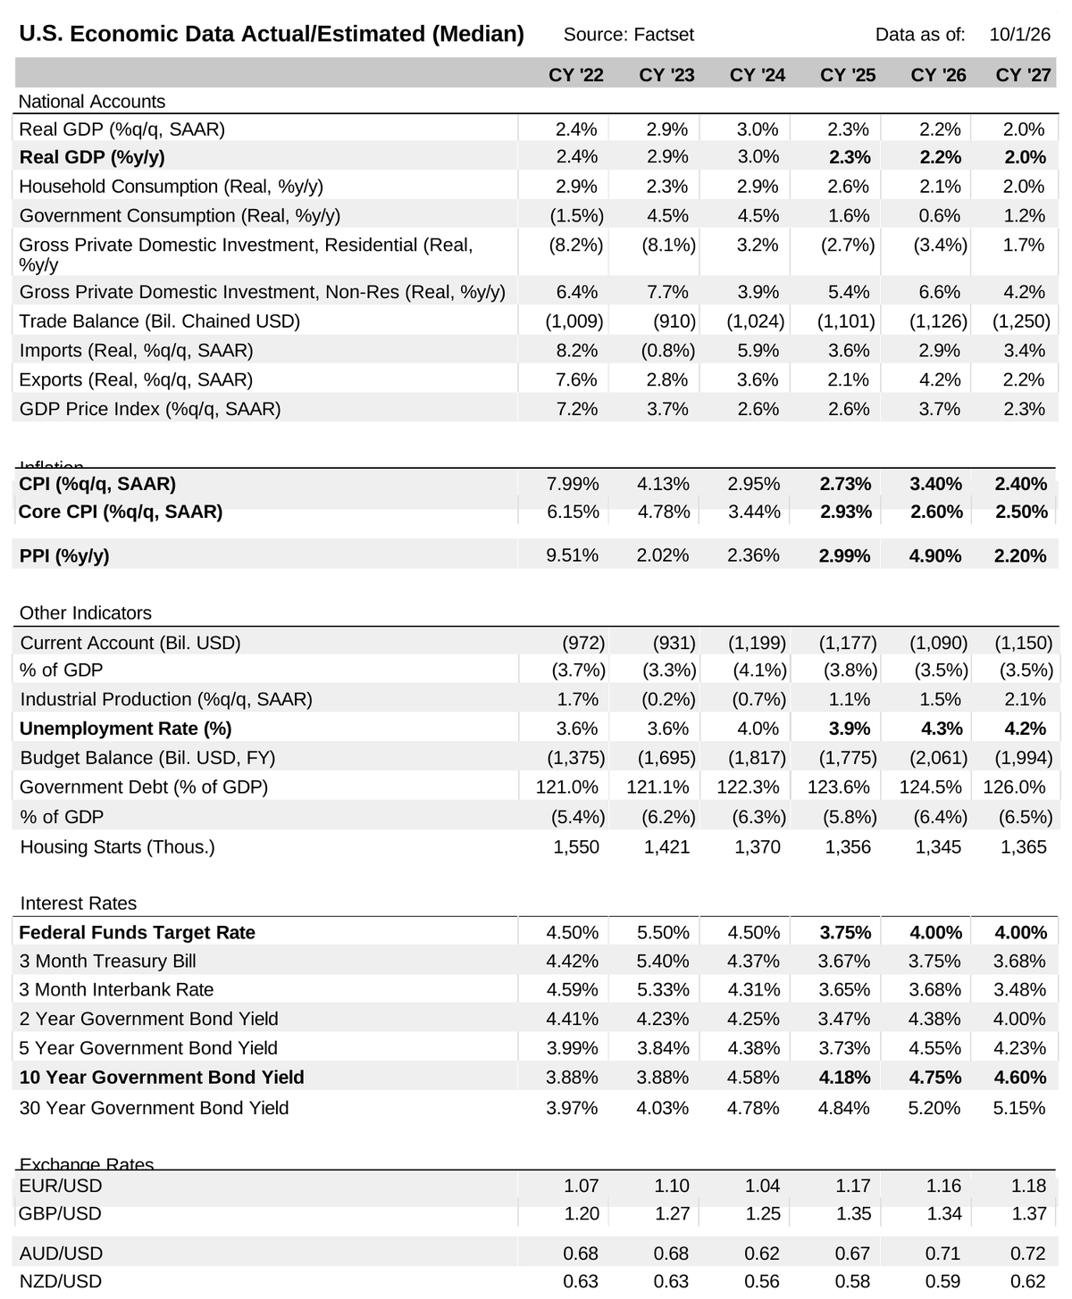
While we haven’t seen much of the negative impact of August and September’s spike in diesel hit food prices (August CPI data), the Fed, consensus and bond yields suggest that more upward pressure is expected. The 10-year Treasury note yield is 5.25%, up a little more than 50bp in the last month.
At this point the main driver appears to be the drop in global refining activity and exports. China is the largest refiner in the world, but the constraint on its oil from the Strait has kept more diesel at home than for export. The US is the second largest refiner in the world. Russia is #3, and it refining output is estimated to be down more than 30% to 3.8mmbpd, it’s lowest in 20 years, mostly as a result of the ongoing war with Ukraine related to drone strikes.
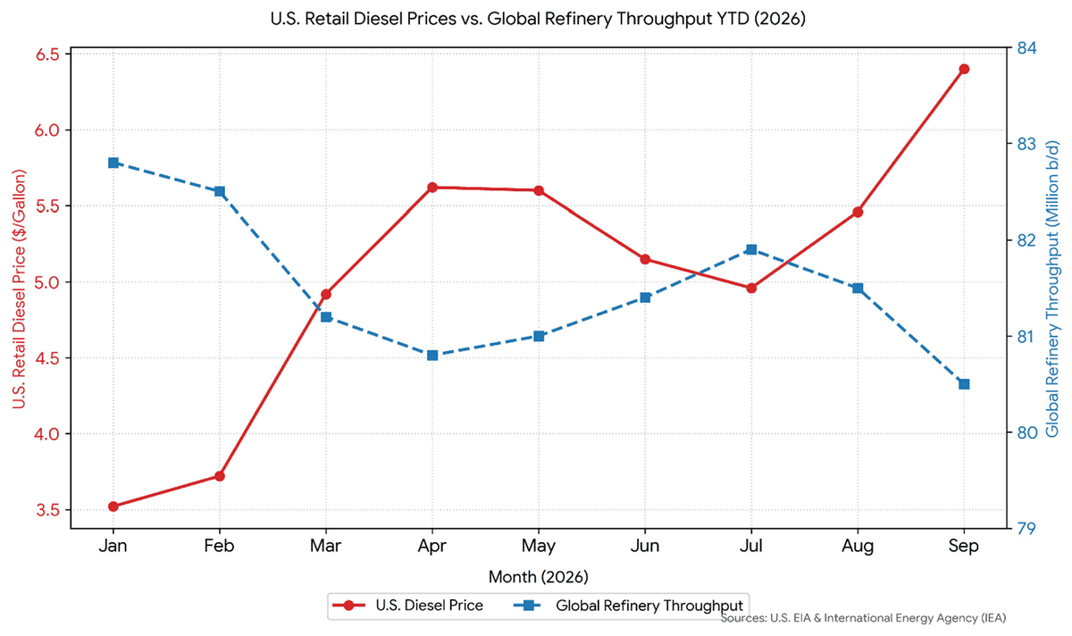
In our view the US-Iran war is the most significant potential offset to the positive trends still driving employment, income, spending and corporate profits. We’ve certainly been through wild oil and gas swings before, but higher inflation, bond yields and policy rates may be more protracted if a sea change isn’t soon in the offing.
Source: Factset
